 EN

The introduction of corporate tax in the UAE has made tax registration, financial reporting, and timely filing important responsibilities for businesses operating in the country. Companies must understand their obligations under the UAE Corporate Tax Law to avoid penalties and maintain proper financial records.
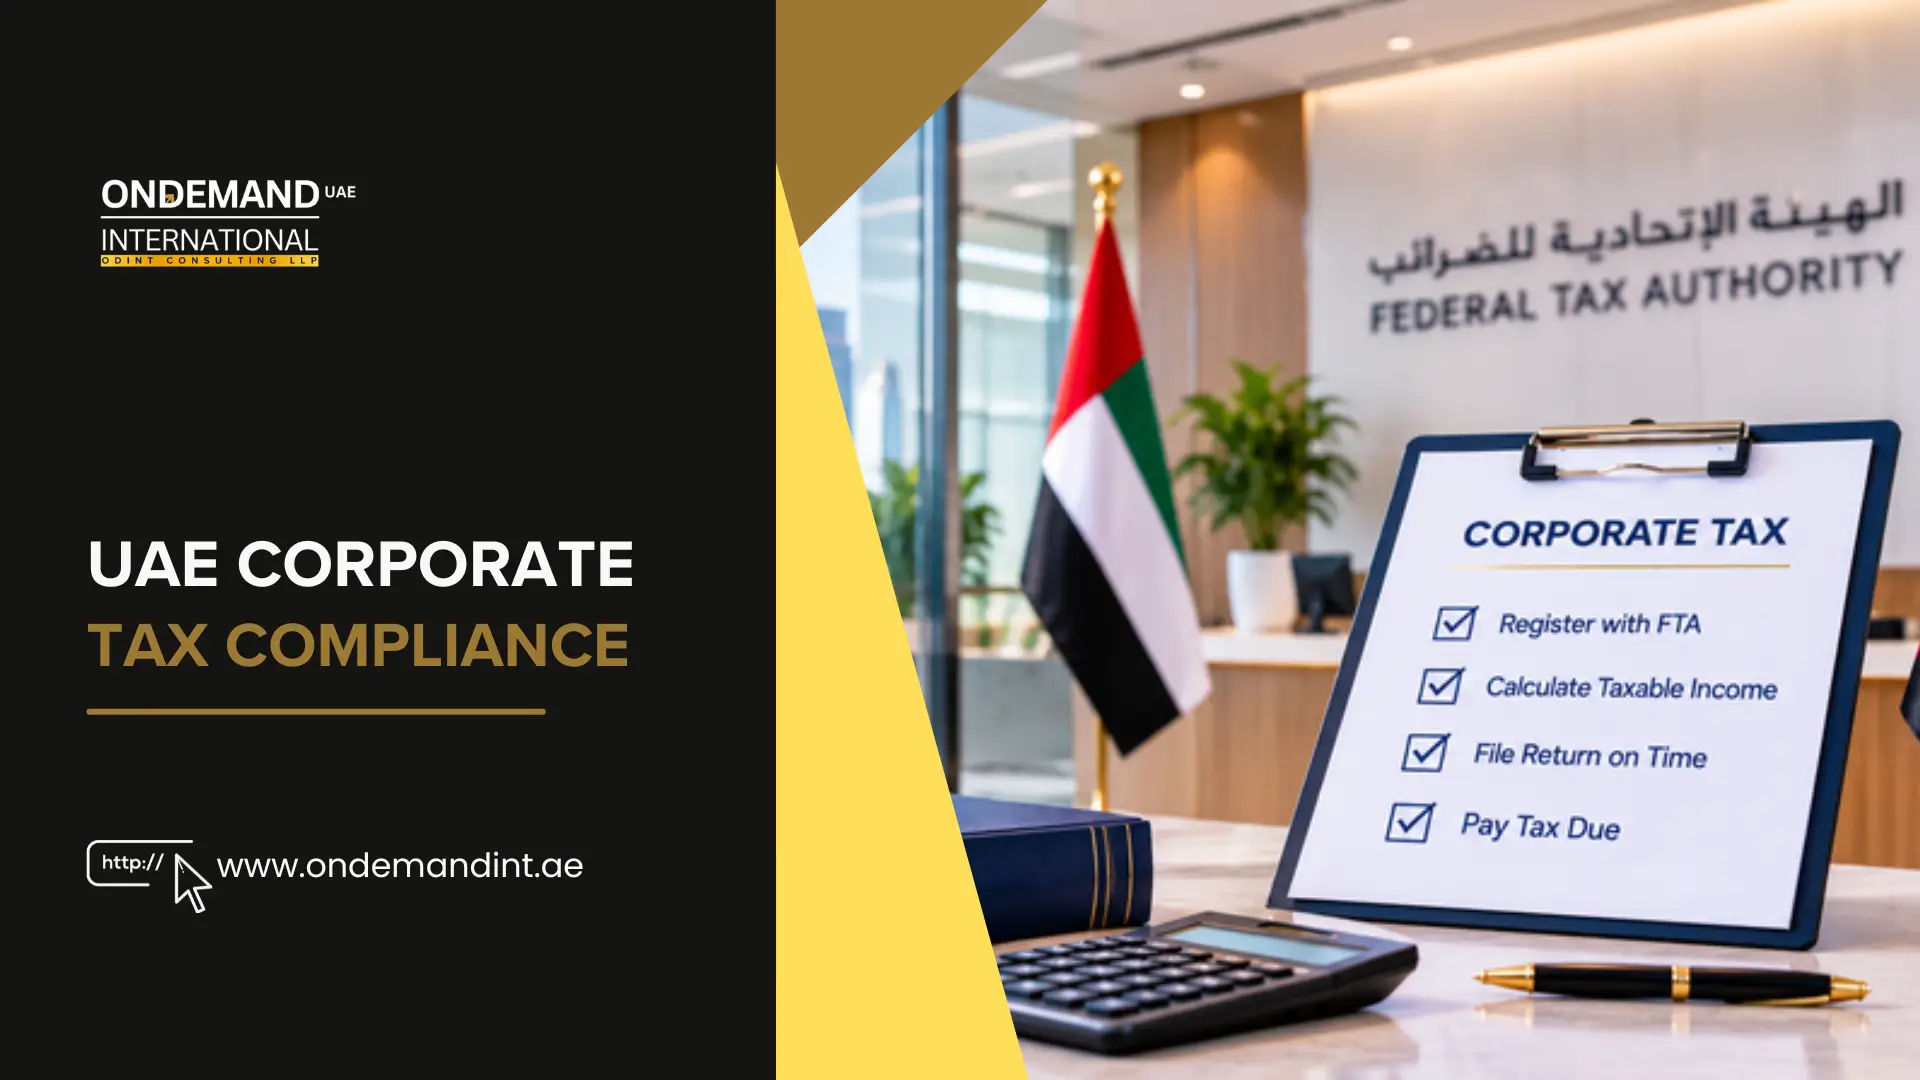
UAE corporate tax compliance involves registering with the Federal Tax Authority (FTA), calculating taxable income, submitting corporate tax returns, and paying any tax due within the prescribed deadlines. Whether you operate a mainland company, a free zone business, or an international company with a taxable presence in the UAE, understanding these requirements helps you manage your tax responsibilities effectively.
What Is UAE Corporate Tax Compliance?
UAE corporate tax compliance involves meeting the legal and financial obligations outlined in Federal Decree-Law No. 47 of 2022 (as amended). The law mandates that taxable businesses determine their taxable income, declare their tax position, and file and pay the tax on time.
The UAE corporate tax regime will be applicable to financial years that started on or after 1 June 2023. It has the following primary compliance requirements:
- Tax registration: Registration with the FTA within the required timeframe.
- Tax calculation: The amount of income that remains after adjustments and deductions.
- Return filing: Filing an annual tax return for the company with EmaraTax.
- Tax payment: Paying the amount due within the prescribed timeframe.
- Record-keeping: Keeping financial statements, invoices, and supporting documents.
- Transfer pricing: Applying the arm’s length principle to related party transactions.
Compliance with the UAE Corporate Tax also includes keeping up with proper bookkeeping. Businesses should make sure accounting information backs up the numbers claimed on their tax returns.
Which Businesses Need to Comply With UAE Corporate Tax?
The majority of companies and businesses in the UAE are in the corporate tax regime, but some companies and income types are exempt or taxed under special conditions.
The following are the key categories:
- Mainland companies: Generally, LLCs and other incorporated companies are in the corporate tax regime.
- Free Zone companies: Businesses are required to register and adhere to corporate tax obligations even if they qualify for the 0% rate for qualifying income.
- Foreign companies: Foreign businesses with a permanent establishment in the UAE may be liable to corporate tax on such attributable income.
- Individual business owners: Natural persons who run a business in the UAE are usually covered by the regime if their annual business turnover is more than AED 1 million.
- Exempt entities: Certain government entities, qualifying public benefit entities, and other specified organizations may qualify for exemptions under the law.
Wages, personal investment income, and qualifying personal real estate investment income of natural persons are generally outside the scope of UAE corporate tax.
Businesses should assess their legal status and activities to determine whether registration, filing, or other compliance obligations apply.
What Are the UAE Corporate Tax Rates, and How Is Taxable Income Calculated?
The UAE applies a standard corporate tax rate of 0% on taxable income up to AED 375,000 and 9% on the amount exceeding this threshold.
| Taxable income | Tax rate |
|---|---|
| Up to AED 375,000 | 0% |
| Above AED 375,000 | 9% |
For example, if a company’s taxable income is AED 600,000, the first AED 375,000 is taxed at 0%, while the remaining AED 225,000 is taxed at 9%. Its corporate tax liability would therefore be AED 20,250.
How is taxable income calculated?
Taxable income is calculated using accounting profit before tax as the starting point, followed by adjustments required under the Corporate Tax Law.
These adjustments may include:
- Deducting eligible business expenses.
- Excluding qualifying exempt income.
- Adding back non-deductible expenses.
- Adjusting income and expenses from related-party transactions.
- Applying eligible tax reliefs and deductions.
Qualifying Free Zone Persons may benefit from a 0% rate on qualifying income, while their non-qualifying taxable income is generally subject to 9%, subject to the applicable rules.
What Are the Key UAE Corporate Tax Compliance Requirements?
To fulfill UAE corporate tax compliance, businesses are required to register for corporate tax, keep accurate financial records, file returns, and, if applicable, pay the tax.
- Corporate Tax Registration: Companies that are liable to corporate tax need to be registered by the FTA on EmaraTax within the prescribed timelines. Typically, documents include a trade license, incorporation documents, shareholder information, and authorized signatory information.
- Corporate Tax Return Filing: Taxable persons are normally required to file one corporate tax return per tax period. The return should provide accurate accounting information, taxable income, adjustments, and tax liability.
- Corporate Tax Payment: Companies are required to pay their corporate tax obligation within 9 months from the end of the tax period. Businesses can avoid late payment penalties by strategically timing their tax payments.
- Financial Record-Keeping: Financial statements, invoices, bank statements, contracts, and supporting documents must be kept by companies. The taxable persons or the relevant exempt persons should keep these records for at least 7 years after the end of the relevant tax period.
- Transfer Pricing Compliance: If businesses enter into transactions with related parties or connected persons, they should adhere to the arm’s length principle. Depending on applicable thresholds, they may also need to submit a Transfer Pricing Disclosure Form and prepare Master File and Local File documentation.
- Free Zone Compliance: Free Zone businesses that are claiming Qualifying Free Zone Person status must satisfy the conditions for the status, such as sufficient UAE substance, qualifying income, transfer pricing compliance, and the requirement for audited financial statements.
When Must Companies File and Pay UAE Corporate Tax?
Companies must generally submit their corporate tax returns and pay the tax due within nine months from the end of their relevant financial year.
For example:
| Financial year-end | Filing and payment deadline |
|---|---|
| 31 December 2025 | 30 September 2026 |
| 31 March 2026 | 31 December 2026 |
| 30 June 2026 | 31 March 2027 |
These deadlines apply to the corresponding tax periods. Corporate tax registration deadlines are separate and depend on the applicable FTA registration rules.
Businesses can complete registration, submit returns, and make payments through the EmaraTax platform.
What Corporate Tax Compliance Rules Apply to Small Businesses?
Small businesses may benefit from Small Business Relief (SBR), which simplifies their corporate tax obligations when they meet the eligibility requirements.
Under the current rules, eligible UAE resident taxable persons can elect for this relief if their revenue does not exceed AED 3 million in the relevant and previous tax periods, subject to the applicable conditions.
The relief has been extended to tax periods ending on or before 31 December 2029.
To qualify, businesses must generally:
- Meet the AED 3 million revenue threshold.
- Be a UAE resident taxable person.
- Not be a Qualifying Free Zone Person.
- Not be a member of a multinational enterprise group exceeding the applicable revenue threshold.
Small Business Relief does not remove all compliance obligations. Eligible businesses must still register where required, elect for the relief in their tax return, submit the return on time, and maintain appropriate financial records.
What Penalties Can Businesses Face for UAE Corporate Tax Non-Compliance?
Businesses that fail to meet their corporate tax obligations may face administrative penalties, additional tax costs, and compliance issues with the FTA.
Some common violations include:
| Non-compliance | Potential penalty |
|---|---|
| Late corporate tax registration | AED 10,000 |
| Late corporate tax return filing | AED 500 per month for the first 12 months, increasing to AED 1,000 per month thereafter |
| Late tax payment | Applicable late-payment penalties |
| Failure to maintain required records | Applicable administrative penalties |
The FTA also implemented a late registration penalty waiver program for businesses that register for taxes or register for the annual declaration for the first time within seven months of the end of their first tax period or fiscal year.
Keeping correct records, tracking deadlines, and checking tax calculations may prevent businesses from getting unnecessary penalties.
How Can Entrepreneurs Maintain UAE Corporate Tax Compliance?
To keep their business tax compliant, entrepreneurs must have proper accounting procedures in place, adhere to the tax filing deadlines, and regularly check their financial records.
Here are some practices that can help:
- Maintain accurate accounts: Track your business income and expenses and business transactions regularly.
- Track tax deadlines: Registration, return filing, and payment deadlines.
- Review taxable income: determine deductible expenses, exempt income, and non-deductible expenses.
- Check related-party transactions: Make sure that transactions are conducted on an arm’s length basis.
- Organize financial documents: Have invoices, contracts, bank statements, and supporting documents easily accessible.
- Monitor regulatory changes: Keep track of the FTA and Ministry of Finance updates.
- Seek professional guidance: When involved in complex transactions or tax obligations, seek guidance from qualified tax professionals.
By following these practices, UAE tax and accounting responsibilities can be better managed for business owners.
How Can OnDemand International Help With UAE Corporate Tax Compliance?
OnDemand International assists businesses in understanding the UAE regulatory requirements as well as the tax and accounting considerations that are relevant to them. Corporate tax compliance guidance can be discussed with the OnDemand International team, such as:
- Corporate tax registration process and documentation.
- Knowledge of relevant corporate taxation issues.
- Documentation requirements for financial records and accounts.
- Preparation and procedures for corporate tax filing.
- Free Zone tax considerations.
- Ongoing regulatory compliance requirements.
For new businesses or operations, consulting a professional can help you learn more about your corporate tax obligations and prepare your compliance activities. Contact OnDemand International to discuss your UAE business requirements and explore suitable corporate tax compliance support.
Conclusion
UAE corporate tax compliance involves managing corporate registration, tax calculations, financial management, return filing, and payments in compliance with the prevailing tax laws. Businesses should also check their transfer pricing responsibilities and assess the availability of particular tax reliefs.
Keeping up-to-date records, tracking deadlines, and keeping yourself updated on regulatory updates will help manage tax obligations and minimise compliance risks for entrepreneurs and business owners.
FAQs
Is UAE corporate tax compliance mandatory for all companies?
Most UAE mainland and free zone companies must comply with corporate tax requirements. However, certain entities and income categories may qualify for exemptions or special tax treatments.
What is the corporate tax rate in the UAE?
The standard rate is 0% on taxable income up to AED 375,000 and 9% on the amount exceeding AED 375,000. Qualifying Free Zone Persons may receive a 0% rate on qualifying income.
What is the penalty for late corporate tax registration in the UAE?
The administrative penalty for late corporate tax registration is AED 10,000. Eligible businesses may qualify for the FTA‘s penalty waiver initiative if they meet its conditions.